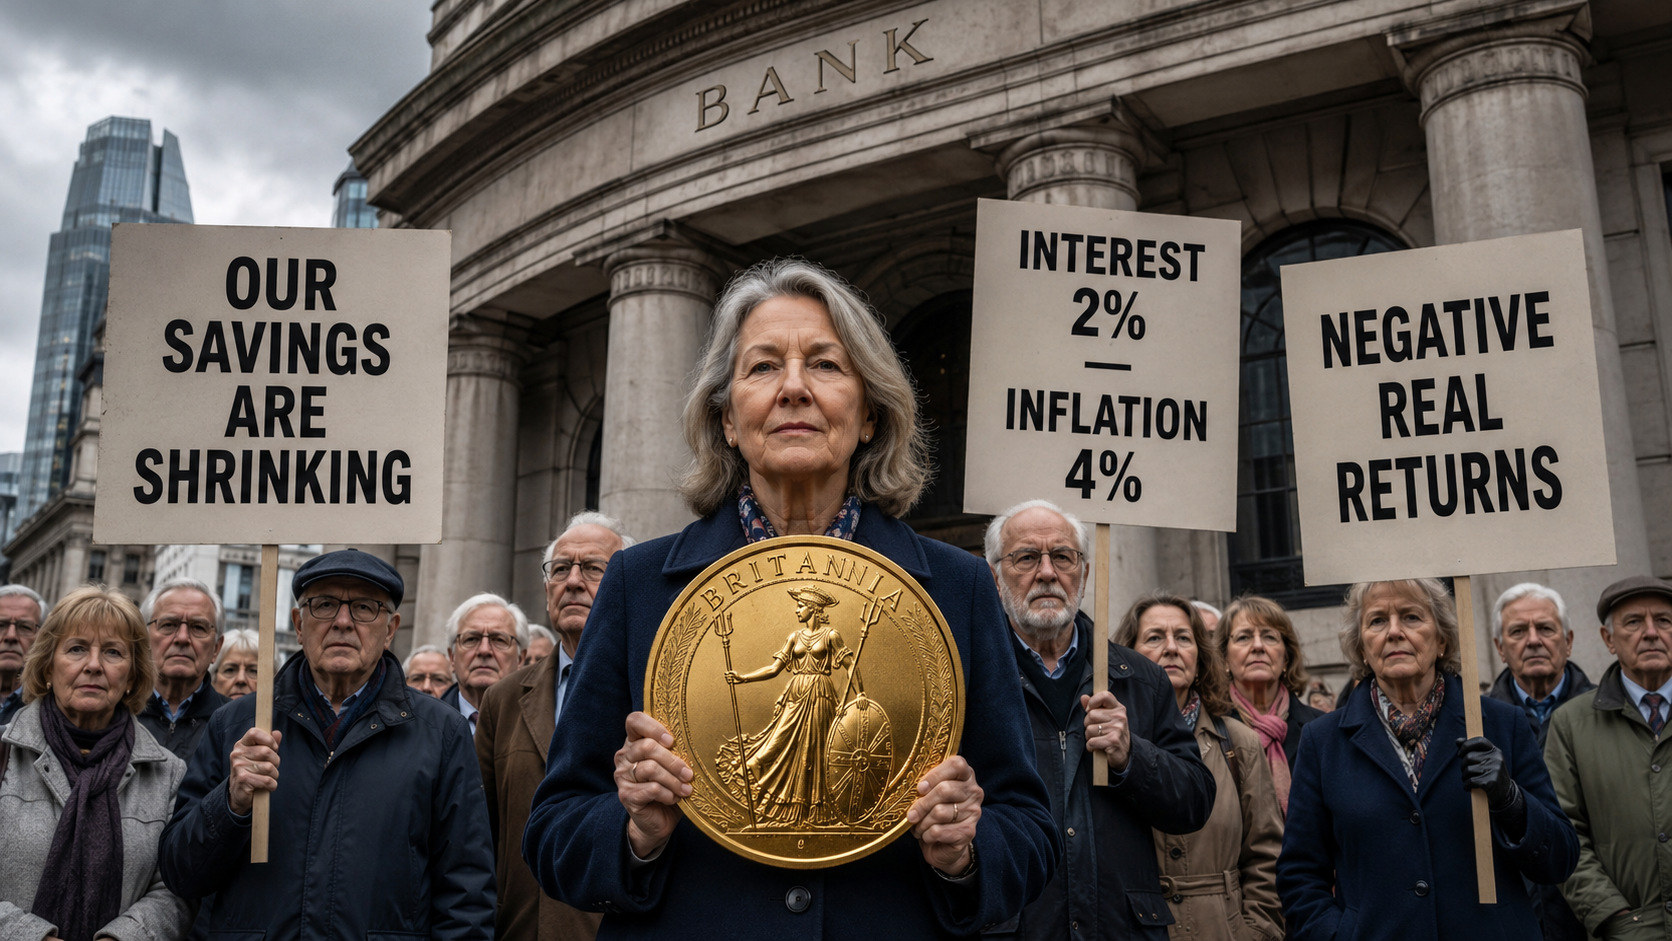
Your Savings Are Growing. Your Wealth Is Shrinking.
The return of negative real rates — and why gold matters when inflation outruns the bank
There is a particularly dangerous kind of financial loss because, on paper, it does not look like a loss at all.
Your bank balance rises. Interest is added. Nothing has been stolen and no investment statement shows a fall. Yet, when you come to use that money, it buys less than it did before.
This is a negative real return — and it is one of the quietest ways in which savers can become poorer.
For millions of people who have spent decades building cash reserves, this matters enormously. The risk is not necessarily that the number in the account falls. The risk is that the life the money was meant to pay for becomes steadily more expensive while the savings fail to keep up.
What is a negative real rate of return?
A savings account pays a nominal rate: the percentage printed on the account.
Your real rate of return is what remains after inflation has taken its share. For most savers, tax must then be considered too.
In simple terms:
Real return = interest earned after tax – inflation
Suppose £100,000 is left in an account paying 2% interest. After one year, it has earned £2,000 before tax.
If inflation is 2.9%, however, the goods and services that cost £100,000 a year earlier now cost approximately £102,900. The account has grown, but not quickly enough.
For a higher-rate taxpayer with a £500 Personal Savings Allowance, tax reduces that £2,000 of interest to approximately £1,400. The saver’s balance has risen to £101,400, but it is £1,500 short of the amount required merely to maintain the same purchasing power.
They have made money in pounds and lost money in reality.
Why negative real returns are so damaging
Inflation does not usually arrive as a single dramatic bill. It compounds quietly through food, energy, insurance, travel, care costs, home maintenance and almost everything else a person expects their savings to fund.
A gap of 1% may appear harmless. It is not. If savings underperform inflation by 1% every year, £100,000 loses roughly £9,500 of purchasing power over ten years. At a 1.5% annual shortfall, the loss is around £14,000. At 3%, almost £26,000 of real value disappears.
The money is still there. Its usefulness is not.
That distinction is particularly important for retirees and people approaching retirement. A salary may rise with inflation; a fixed pot of cash cannot replenish itself. Once purchasing power has been lost, taking greater risk later in an attempt to recover it may create a second problem.
Cash can therefore be safe in nominal terms but risky in real terms.
Tax makes the gap wider
The advertised savings rate is not necessarily the rate a saver keeps.
Basic-rate taxpayers currently have a £1,000 Personal Savings Allowance and higher-rate taxpayers £500. Additional-rate taxpayers receive no allowance. Interest above the allowance is taxed at the saver’s marginal rate.
This matters much more when large sums are held in cash. At 4% interest, £100,000 generates £4,000 a year. Much of that interest may be taxable, depending on the saver’s circumstances and where the money is held.
From April 2027, the tax rates applied to savings income are scheduled to rise by two percentage points: to 22%, 42% and 47%. The Personal Savings Allowances are set to remain unchanged.
Even a competitive headline rate can therefore become a very modest real return after tax. And an old account paying a poor rate can become a guaranteed erosion of wealth.
Are savers already in negative territory?
Some are; some are not.
UK CPI inflation rose to 2.9% in July 2026, while the broader CPIH measure reached 3.1%. The Bank of England’s base rate is currently 3.75%, and the best easy-access accounts have recently offered around 4.5% before tax.
That means an active saver using one of the strongest accounts may still beat today’s reported inflation. But several warnings sit behind that reassuring headline:
- The Bank Rate is not the rate every bank pays its customers.
- Leading rates may include temporary bonuses, balance limits or withdrawal restrictions.
- Many older accounts pay much less than the market leaders.
- Tax can remove much or all of the margin above inflation.
- Today’s interest rate is being compared with yesterday’s inflation data.
- A new energy shock can lift inflation much faster than banks lift deposit rates.
The honest conclusion is not that every savings account is currently losing money. It is that every saver must calculate their own after-tax real return — and must keep recalculating it.
Can we forecast the return of negative real rates?
Not with precision, because both sides of the equation can move. Savings rates may rise or fall, inflation can surprise, and tax circumstances differ.
But the risk can be stress-tested.
Take the rate your account actually pays. Deduct any likely tax. Then compare the result not only with today’s inflation, but with inflation at 4%, 5% or 6%.
If your savings pay 3% after tax and inflation returns to 5%, your real return is approximately minus 2% a year. On £100,000, that is around £2,000 of lost purchasing power in the first year alone. If the gap persists, the damage compounds.
The important question is therefore not:
“What interest rate am I receiving today?”
It is:
“What could my money earn after tax if inflation rises again — and will that be enough?”
Unfortunately, the conditions for another inflation shock are already visible.
Oil is not just another commodity price
When oil rises, the cost does not stop at the petrol station.
Oil powers transport, agriculture, construction, manufacturing and global shipping. It is used in plastics, chemicals, packaging and countless industrial processes. Diesel moves food from farms to warehouses and shops. Jet fuel moves people and high-value goods. Natural gas affects heating, electricity, fertiliser and food production.
A sustained rise in oil and gas prices can therefore pass through the economy in waves:
- Petrol, diesel, aviation and household energy become more expensive.
- Businesses face higher transport, production and packaging costs.
- Those costs are passed to customers through higher prices.
- Workers seek higher wages to meet the increased cost of living.
- Inflation becomes broader and more persistent.
This creates the central banker’s nightmare: inflation rises while economic growth weakens.
Interest rates may need to remain high to fight inflation, even as households and businesses struggle. Alternatively, rates may be cut to support a weakening economy before inflation has been defeated. Either route can be painful — and neither guarantees that savers receive a positive real return.
What if the Strait of Hormuz remains effectively closed?
The Strait of Hormuz is not a distant geopolitical detail. It is one of the most important economic arteries in the world.
Before the current conflict, around 20 million barrels of oil a day passed through it — approximately a quarter of all seaborne oil trade. Qatar and the United Arab Emirates also sent volumes equivalent to almost one-fifth of global liquefied natural gas trade through the Strait.
There are pipelines that can bypass Hormuz, but their estimated spare capacity is only around 3.5 to 5.5 million barrels a day. They cannot replace the Strait in full.
The disruption is already substantial. The International Energy Agency reported in August that Gulf oil output remained 8.3 million barrels a day below pre-war levels and that observed global oil inventories had fallen by 410 million barrels since the conflict began. Refining margins for diesel, jet fuel and petrol have been driven sharply higher by supply shortages and depleted stocks.
There is also a large gap between official claims of recovering traffic and independent shipping data. Kpler tracking cited by Reuters estimated that only 2.3 million barrels a day of crude passed through Hormuz during August, compared with 15.82 million barrels a day in the three months before the war.
If restricted flows persist, the danger is not simply a higher oil price on a financial screen. It is a chain reaction:
Less oil and gas → higher energy and transport costs → higher business costs → higher consumer prices → lower real returns for savers
Emergency reserves and reduced demand can soften the blow for a time. A ceasefire or lasting navigation agreement could also improve the outlook. But reserves are finite, alternative routes are limited, and damaged inventories take time to rebuild.
The longer the disruption continues, the greater the risk that an energy shock becomes a wider inflation shock.
What should savers do if their real return is negative?
The answer is not to abandon cash. Cash remains essential for emergencies, planned expenditure and near-term security.
The answer is to stop treating all cash as automatically safe simply because its pound value does not move.
A sensible review should include five steps:
1. Calculate the real return
Check the actual rate on every account, including what happens when any introductory bonus expires. Estimate the interest after tax and compare it with inflation.
2. Use the available tax shelters
Cash ISAs and other legitimate allowances can protect interest from tax. The correct structure depends on individual circumstances, so professional tax or financial advice may be appropriate.
3. Keep necessary cash — but give every pound a purpose
Money needed for emergencies or spending in the next few years should not be exposed to inappropriate risk. Cash held with no timeframe and no purpose, however, deserves closer scrutiny.
4. Shop around and check protection limits
Do not assume loyalty will be rewarded. Compare rates, withdrawal rules, bonus periods and deposit-protection arrangements.
5. Diversify the portion intended for longer-term wealth preservation
No single asset should be expected to solve every problem. Diversification can reduce dependence on one bank, one currency and one economic outcome.
This is where gold can play an important role.
Why gold matters when real rates turn negative
Gold pays no interest. In an environment where cash produces a strong, reliable return above inflation, that can appear to be a disadvantage.
But when the after-tax return on cash falls below inflation, the comparison changes. The “yield” on cash may be positive in name only, while gold’s lack of interest becomes less important.
Gold has several characteristics that become especially valuable in this environment:
- It is scarce and cannot be created by a central bank.
- It is a physical asset that can be owned outright.
- It does not depend on a bank, company or government meeting a future payment.
- It is traded globally and valued in multiple currencies.
- It has historically become more attractive when real yields fall and investors seek protection from inflation, currency weakness and financial stress.
For UK investors, qualifying investment gold is exempt from VAT. UK legal-tender bullion coins such as Britannias and Sovereigns also have the advantage of being exempt from Capital Gains Tax for UK residents under current rules.
Gold is not a savings account. Its price can rise and fall, it does not generate income, and it should not replace the cash needed for bills or emergencies. Nor does it rise in every inflationary month.
Its role is different.
Gold can provide a form of financial insurance: a separately held, finite asset intended to help preserve purchasing power when cash, currencies and confidence are under pressure.
The same oil shock that damages the real value of cash can strengthen several of gold’s traditional drivers at once — inflation fears, geopolitical uncertainty, pressure on currencies and demand for assets outside the banking system.
That is why gold and oil can rise together. Oil may be the source of the inflationary problem; gold may be one part of the response.
The real risk is doing nothing
Savers are often described as cautious. But leaving a large sum in a low-paying, taxable account while inflation compounds is not necessarily caution. It can be a decision to accept a loss that is difficult to see and impossible to recover without future growth.
The number on a bank statement tells you how many pounds you have. It does not tell you what those pounds can still buy.
With inflation rising again, savings tax due to increase and one of the world’s most important energy routes still severely disrupted, now is the time to look beyond the headline interest rate.
Keep the cash you need. Make it work as hard and tax-efficiently as possible. Then consider whether a portion of your longer-term savings should be moved from a promise measured in pounds into something real, finite and independently valuable.
Because protecting wealth is not about preserving a number.
It is about preserving what that number can do for you and the people you intend to leave it to.
Sources and publication notes
- Office for National Statistics, Consumer price inflation, UK: July 2026.
- Bank of England, Monetary Policy Report: July 2026.
- Moneyfactscompare, UK easy-access savings rates, accessed 27 August 2026.
- HM Revenue & Customs, Tax on savings interest and changes to savings-income tax rates.
- International Energy Agency, Oil Market Report: August 2026 and Strait of Hormuz oil-security data.
- Reuters, Asia’s crude oil imports stay soft in August, challenging US Hormuz claims, 27 August 2026.
- HM Revenue & Customs, Investment gold coins and VAT.
- The Royal Mint, Gold bullion coins and Capital Gains Tax.
- J.P. Morgan Private Bank, Is it a golden era for gold?, February 2026.
Compliance note: This article is for general information and educational purposes only. It does not constitute personal financial, investment, legal or tax advice. The value of gold can fall as well as rise. Tax treatment depends on individual circumstances and may change. Readers should seek suitably qualified independent advice before making financial decisions.
About the Author
Matthew Jones is Co-Founder and Precious Metals Analyst at Britannia Bullion. With a background in financial markets and precious-metals trading, Matthew writes about gold, inflation, geopolitics and the changing global financial system.
|
Matthew Jones Co-Founder Precious Metals Analyst Britannia Bullion |