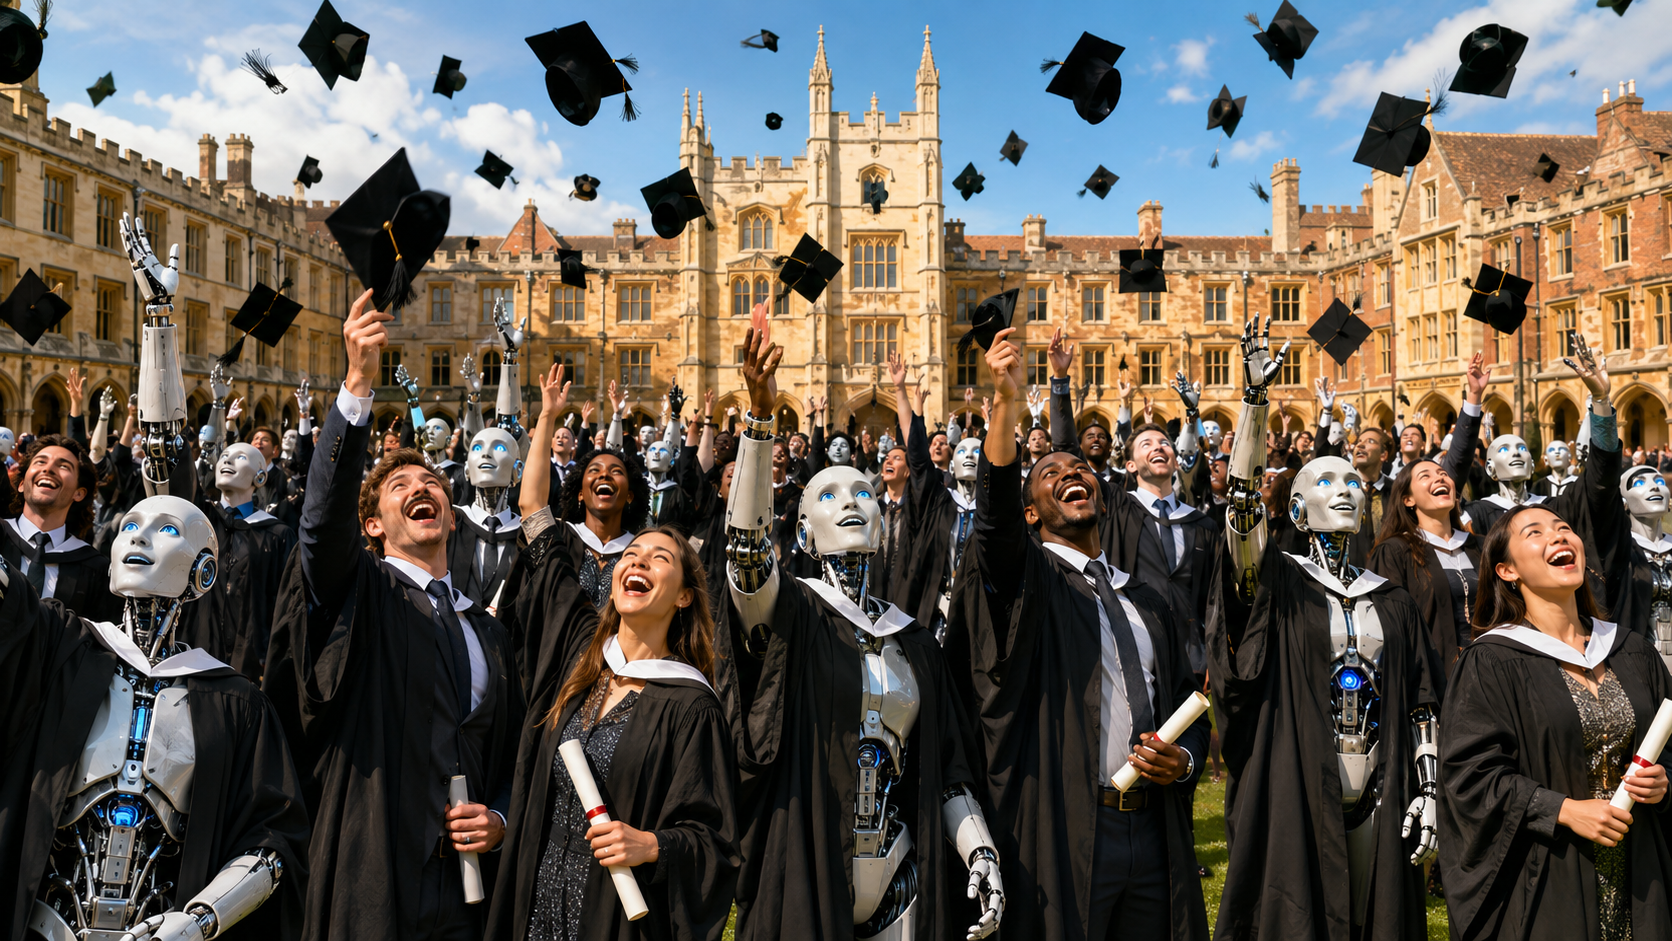
UK graduate vacancies have fallen by almost 50% in a single year. Is this simply a weak jobs market—or the first visible sign that the traditional career ladder is beginning to disappear?
By Matthew Jones, Co-founder and Precious Metals Analyst at Britannia Bullion
In July 2025, the recruitment platform Adzuna carried 15,397 UK graduate vacancies.
One year later, it carried just 8,383.
In twelve months, the number of advertised graduate roles had fallen by 45.6%. It was the lowest figure recorded since Adzuna began tracking the market in 2016. At its 2017 peak, the platform carried more than 55,000 graduate vacancies. The July figures were reported by The Guardian and Business Insider.
This does not mean that half of all graduate jobs in Britain have disappeared. It measures advertised vacancies on one major recruitment platform, not total graduate employment. Wider entry-level vacancies fell by a much smaller 8.1% over the same year.
But that qualification should not make the headline comfortable.
A fall of almost 50% is not a statistical wobble. Graduate vacancies were already down 42.1% year-on-year in May. By July, the decline had deepened. This is happening as more than one million people aged 16 to 24 are already outside education, employment or training.
The question is no longer whether the graduate jobs market is under pressure. It plainly is.
The question is whether we are witnessing a temporary downturn—or the beginning of something much larger.
The first rung of the ladder
For generations, the economic bargain offered to young people was relatively straightforward.
Study hard. Gain qualifications. Enter at the bottom of a profession. Learn from experienced colleagues. Become productive. Earn more. Pay more tax. Rent or buy a home. Start a family. Save into a pension.
The entry-level job was never merely a salary. It was the first rung of the ladder on which the rest of an adult economic life was built.
Artificial intelligence is now particularly capable of performing many of the tasks traditionally given to people standing on that first rung: research, summaries, basic analysis, document preparation, data processing, presentation building, administration and first drafts.
The Bank of England reported in July that automation was already reducing demand for some entry-level and junior positions, including roles involving document preparation, invoice processing and basic analysis. Contacts in professional services also reported lower demand for graduates, administrators and junior employees.
This leads to a crucial distinction in the employment debate:
AI does not have to replace your job to change the labour market. It only has to prevent the next job from being created.
Redundancies make headlines. Missing vacancies do not.
A company that once recruited ten graduates may hire six, then four, while asking a smaller number of experienced employees to produce more with AI. No dismissal is recorded. There may be no dramatic announcement and no factory gates closing. The opportunity simply never appears.
That makes the early stages of automation unusually difficult to see in conventional employment data.
This is not just an AI story
It would be too simplistic to blame the entire fall on artificial intelligence.
British businesses have also faced weak growth, higher employment costs, elevated interest rates and considerable uncertainty. When margins are under pressure, recruitment is often frozen before existing staff are removed. Graduate hiring is particularly vulnerable because training a new employee costs money today in return for productivity tomorrow.
The Institute of Student Employers offers a more measured view than many of the alarming headlines. Its 2026 survey found that 53% of employers expected entry-level recruitment to remain steady over the next three years, while 27% anticipated growth and 17% expected reductions.
Yet the same organisation’s development research found that 87% of employers expect AI to reshape graduate and apprentice roles. Only 40% expected no entry-level roles to be replaced, while 42% anticipated limited replacement and 18% foresaw more substantial losses.
Therefore, this may not be a choice between an ordinary slowdown and an AI revolution. The two forces can reinforce one another.
Economic pressure gives companies a reason to reduce recruitment. AI gives them a means of doing so without suffering the same loss of output.
When the economy eventually improves, the central question will be whether all those graduate vacancies return—or whether businesses discover that they no longer need them.
The end of work—or the end of entry-level work?
The evidence does not support the claim that human work is about to vanish entirely. Graduate employment remains high when measured across the whole working-age population, and many employers continue to invest in young people.
Nor will every role be equally exposed. Work requiring physical presence, human trust, accountability, persuasion, leadership, complex judgement or skilled manual ability may prove more resilient. Entirely new jobs will also be created around AI, just as earlier technologies created occupations that could not previously have been imagined.
But new jobs do not automatically appear in the same place, at the same speed, or for the same people whose opportunities have been removed.
The more immediate threat is to the traditional structure of a career.
Businesses need experienced employees—but experience has always been created by allowing inexperienced people to begin. If AI absorbs the basic work on which young employees once trained, companies could eventually face a paradox: they have removed the junior roles that produced their future senior staff.
The ladder does not have to disappear completely to become much harder to climb. It simply needs fewer rungs, spaced further apart.
The economic chain reaction
The consequences extend far beyond disappointed graduates.
A young person who does not enter stable employment is not only losing a wage. The wider economy loses income-tax and National Insurance receipts. Consumer spending is weaker. Pension contributions are delayed. The ability to rent independently or save a deposit is reduced. Household formation and home ownership may be pushed further into the future.
Multiply that across hundreds of thousands of people and the effects begin to bleed into almost everything: retail demand, rental markets, house purchases, credit growth, pension saving and the public finances.
At the same time, the state may collect less tax while spending more on support, training and welfare. Governments already carrying heavy debt burdens would then be asked to manage a transition in which the link between employment, taxation and public expenditure becomes less dependable.
There is also a lasting human cost. Research on previous labour-market downturns shows that entering work during a weak period can leave scars on earnings for years. An OECD study found that graduates entering a market with youth unemployment five percentage points higher earned approximately 8% less in their first year and 3.5% less five years later.
The first missed opportunity can echo through an entire career.
Productivity for whom?
AI may create extraordinary productivity. That should, in principle, make society wealthier.
But lower corporate costs do not guarantee that prices fall by the same amount, that wages rise, or that the gains are distributed evenly. A business is not a charity. If it can produce more with fewer people, a significant share of the benefit may flow to profits and the owners of capital.
Bank of England Governor Andrew Bailey has acknowledged this risk: if AI mainly replaces labour, employment can fall while the share of income flowing to profits rises relative to wages.
That points towards a deeper economic divide.
Those who own businesses, shares, property or other productive assets may benefit from the technology. Those who rely almost entirely on selling their labour may face greater competition and weaker bargaining power. Younger people—who typically own the fewest assets—could be hit first and hardest.
This does not mean progress should be stopped. It means the gains from progress cannot simply be assumed to distribute themselves fairly.
Why this matters to savers
The collapse in graduate vacancies is not, by itself, an argument to buy gold. It is evidence of something broader: some of the assumptions on which households and governments have planned for the future are becoming less secure.
Our economic system depends on large numbers of people moving into progressively better-paid work, paying tax, consuming, purchasing homes and funding retirement. If that progression weakens, pressure builds elsewhere.
Governments may respond with greater borrowing, subsidies, retraining programmes, tax changes or monetary support. None is cost-free. Some shift the burden onto taxpayers; others onto holders of cash and fixed-income savings through inflation or currency debasement.
Physical gold does not create employment, solve inequality or predict exactly how AI will develop. What it can provide is diversification away from a financial system that depends heavily upon uninterrupted growth, rising tax receipts and confidence in long-term policy management.
Gold is not a bet that every graduate will lose their job.
It is recognition that when the economic foundations begin to move, holding all of your wealth in assets dependent on those foundations may no longer feel adequately diversified.
The beginning?
Perhaps this is simply the low point of a difficult hiring cycle. If growth returns and graduate vacancies recover, the July figure may eventually be remembered as an alarming but temporary collapse.
But there is another possibility.
This may be the moment when economic weakness and rapidly improving technology converged—when companies stopped recruiting during a downturn and later discovered that AI allowed them not to restart.
The end of human employment is not here.
The beginning of the end of entry-level work as we have known it may be.
And if the first rung of the ladder is disappearing, the consequences will eventually be felt far above it.
About the author
Matthew Jones is Co-founder and Precious Metals Analyst at Britannia Bullion. He writes about gold, monetary risk, economic change and the forces reshaping long-term wealth preservation.
Important information
This article is provided for general information and education only. It does not constitute financial, investment, tax or legal advice, or a personal recommendation. The price of precious metals can fall as well as rise, and past performance is not a reliable indicator of future results. Consider your individual circumstances and seek independent professional advice where appropriate.
|
Matthew Jones Co-Founder Precious Metals Analyst Britannia Bullion |