Why Britain’s debt markets may be flashing a warning sign investors cannot afford to ignore.
For years, most investors barely glanced at the bond market.
It was seen as dull. Predictable. Safe.
But today, the UK bond market may be telling us something deeply uncomfortable about Britain’s financial future.
UK government borrowing costs have climbed towards levels not seen in almost three decades. Yields on gilts — effectively the interest rate Britain pays to borrow money — have surged higher at a time when economic growth remains fragile, business confidence subdued and geopolitical tensions continue to escalate globally.
Markets are beginning to ask a difficult question:
Who is going to pay for all of this?
Because Britain now finds itself trapped between two dangerous forces:
- A slowing economy
- And an increasingly expensive debt burden
That combination rarely ends well.
The Bond Market Is Losing Its Patience
Bond markets matter because they are effectively the nervous system of the financial world.
When governments spend heavily and investors remain confident, borrowing costs stay manageable.
But when confidence begins to fade — particularly confidence in future growth, fiscal discipline or political stability — the market demands higher returns for lending money.
That is exactly what appears to be happening now.
Britain already faces enormous structural pressures:
- Weak productivity growth
- High public debt
- Stretched public services
- Persistently elevated inflation
- Rising defence spending requirements
- And now growing geopolitical uncertainty linked to the Middle East and Iran
Energy markets remain highly sensitive to any escalation involving Iran or the Strait of Hormuz. Even the threat of disruption to oil flows has the potential to feed directly into inflation, transport costs and consumer prices across Europe and the UK.
In simple terms:
Just as Britain desperately needs growth, the global environment is becoming increasingly hostile to it.
And markets know it.
Political Risk Could Become Financial Risk
The timing could hardly be worse for Sir Keir Starmer.
Should local election polling prove as poor as some forecasts suggest, pressure inside Labour may intensify rapidly. Political instability is rarely welcomed by financial markets — particularly when the alternatives appear likely to shift even further left economically.
That matters because markets are forward-looking.
If investors begin to believe Britain is heading towards:
- Higher public spending
- Larger deficits
- Increased borrowing
- More state intervention
- And weaker long-term growth
…then bond markets could react aggressively.
The concern is not simply politics itself.
It is the fear that Britain may attempt to spend its way out of stagnation at precisely the moment global capital is becoming far less willing to fund endless deficits cheaply.
That is how debt spirals begin.
And history shows bond markets can turn from calm to chaos very quickly.
We saw a glimpse of this during the 2022 gilt crisis, when markets violently rejected unfunded spending promises and The Bank of England was ultimately forced to intervene to prevent instability spreading through pension funds and wider financial markets.
Many assumed that was a one-off event.
But what if it was actually a warning shot?
Why This Matters Beyond Bonds
Most people do not own government bonds directly.
But almost everybody is exposed to them indirectly.
Bond yields influence:
- Mortgage rates
- Business lending costs
- Pension performance
- Equity valuations
- Government spending capacity
- Currency strength
- And ultimately the cost of living itself
When borrowing costs rise sharply, something eventually breaks.
Sometimes it is housing.
Sometimes it is banking.
Sometimes it is the currency itself.
And sometimes it is confidence.
That is why periods like this tend to create volatility across all financial assets simultaneously.
Equities struggle because growth weakens.
Bonds struggle because debt expands.
Currencies weaken because governments attempt to inflate their way out of trouble.
Investors searching for “safe” traditional assets can suddenly discover there are very few places left to hide.
The Return Of Gold
This is precisely why gold has re-emerged as one of the best-performing major assets of recent years.
Gold carries no counterparty risk.
It cannot be printed.
It is not dependent on a government keeping its promises.
And unlike fiat currencies, gold has survived every major debt crisis, currency devaluation and political experiment throughout recorded history.
For centuries, gold has acted as financial insurance during periods when confidence in governments, currencies and debt markets begins to deteriorate.
Today feels increasingly similar.
Central banks themselves appear to recognise this reality.
Global central bank gold purchases remain near historic highs as nations quietly reduce reliance on debt-based reserve systems and increasingly fragile fiat currencies.
That should tell investors something important.
The smartest money in the world is preparing for instability — not assuming stability.
The Bigger Picture
Britain is not alone.
Across the Western world, governments face the same impossible equation:
- Slowing growth
- Aging populations
- Expanding debt burdens
- Rising geopolitical tensions
- And electorates demanding more spending at precisely the worst possible moment
The old solution was simple:
Lower interest rates and print more money.
But after years of inflation, markets are no longer convinced the system can absorb endless debt without consequences.
That leaves governments trapped.
Raise rates and risk recession.
Cut rates and risk inflation.
Borrow more and spook the bond markets.
Borrow less and risk economic stagnation.
None of these outcomes are particularly comforting for traditional investors.
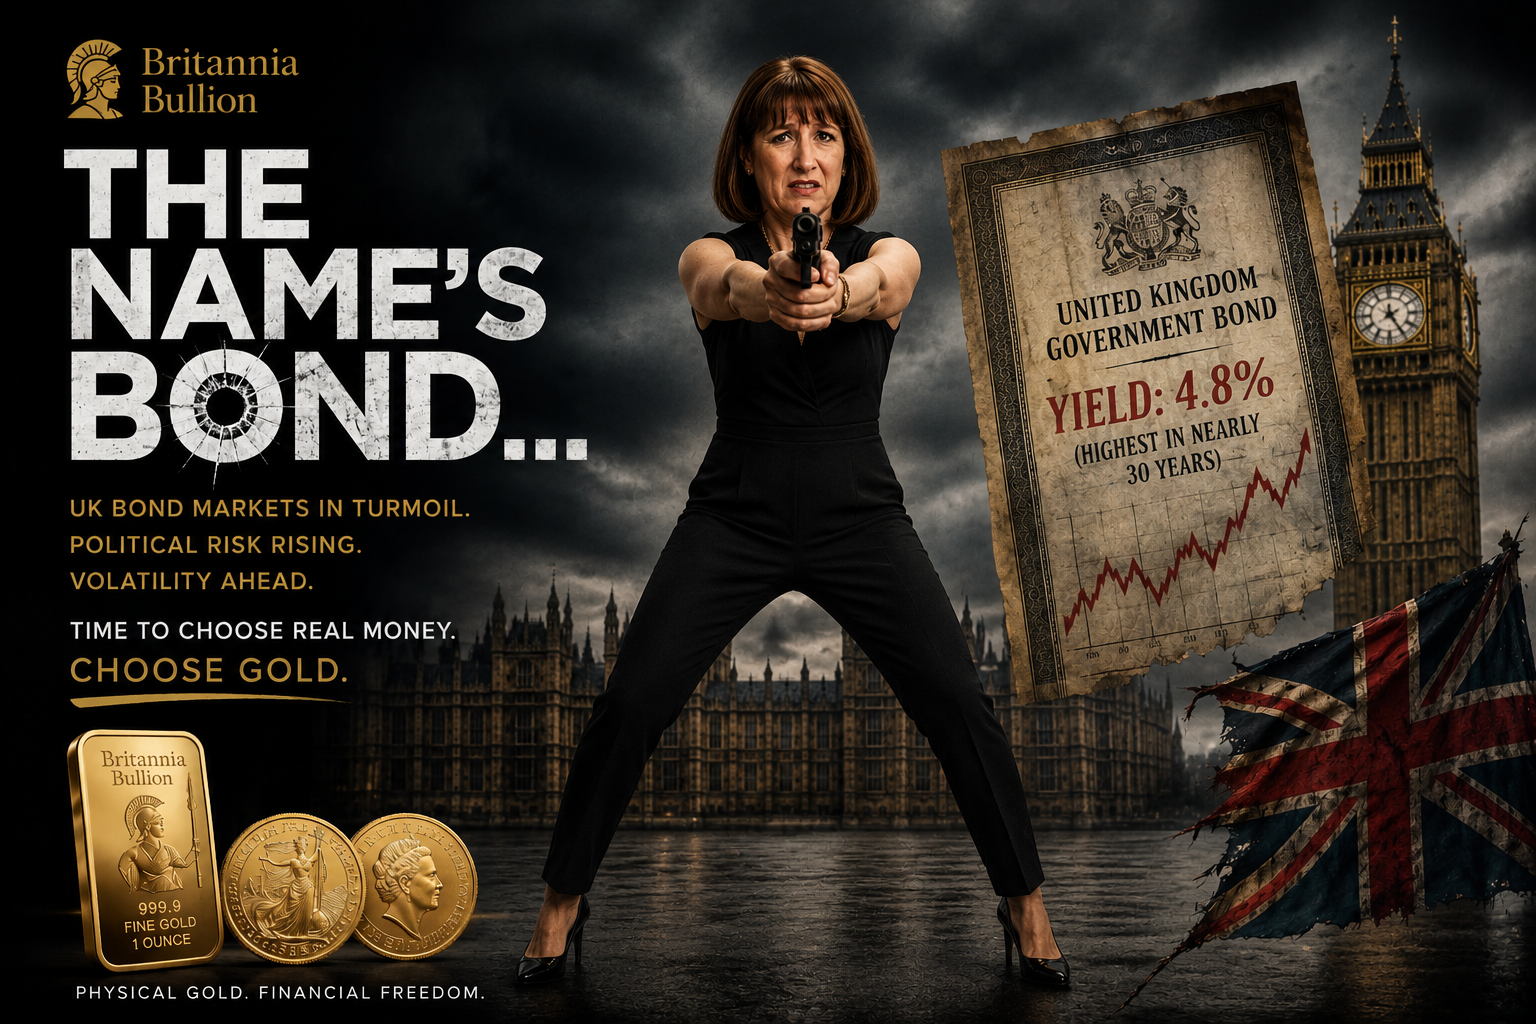
The Name’s Bond… But Gold May Be The Real Safe Haven
The irony is difficult to ignore.
For decades, government bonds were considered the ultimate “risk-free” asset.
Today, many investors are beginning to question whether sovereign debt itself has become one of the greatest risks in the system.
And when confidence in debt begins to crack, history suggests investors eventually migrate back towards real assets.
Towards tangible wealth.
Towards assets that sit outside the financial system entirely.
Towards gold.
At Britannia Bullion, we believe we are entering a period where preserving wealth may become more important than chasing returns.
Because in an age of rising debt, political uncertainty and fragile financial systems, the real question may no longer be:
“What can I make?”
But instead:
“What can I protect?”
And historically, few assets have answered that question more consistently than physical gold.
About the author
Matthew Jones is Co-founder and Precious Metals Analyst at Britannia Bullion. He writes about gold, monetary risk, economic change and the forces reshaping long-term wealth preservation.
Important information
This article is provided for general information and education only. It does not constitute financial, investment, tax or legal advice, or a personal recommendation. The price of precious metals can fall as well as rise, and past performance is not a reliable indicator of future results. Consider your individual circumstances and seek independent professional advice where appropriate.
|
Matthew Jones Co-Founder Precious Metals Analyst Britannia Bullion |