Hormuz May Reopen. It Will Never Be Free Again
The old assumption of unrestricted passage has been destroyed. From now on, the world will pay a permanent security premium—and that cost will eventually reach almost every household.
By Matthew Jones
Co-Founder and Precious Metals Analyst at Britannia Bullion
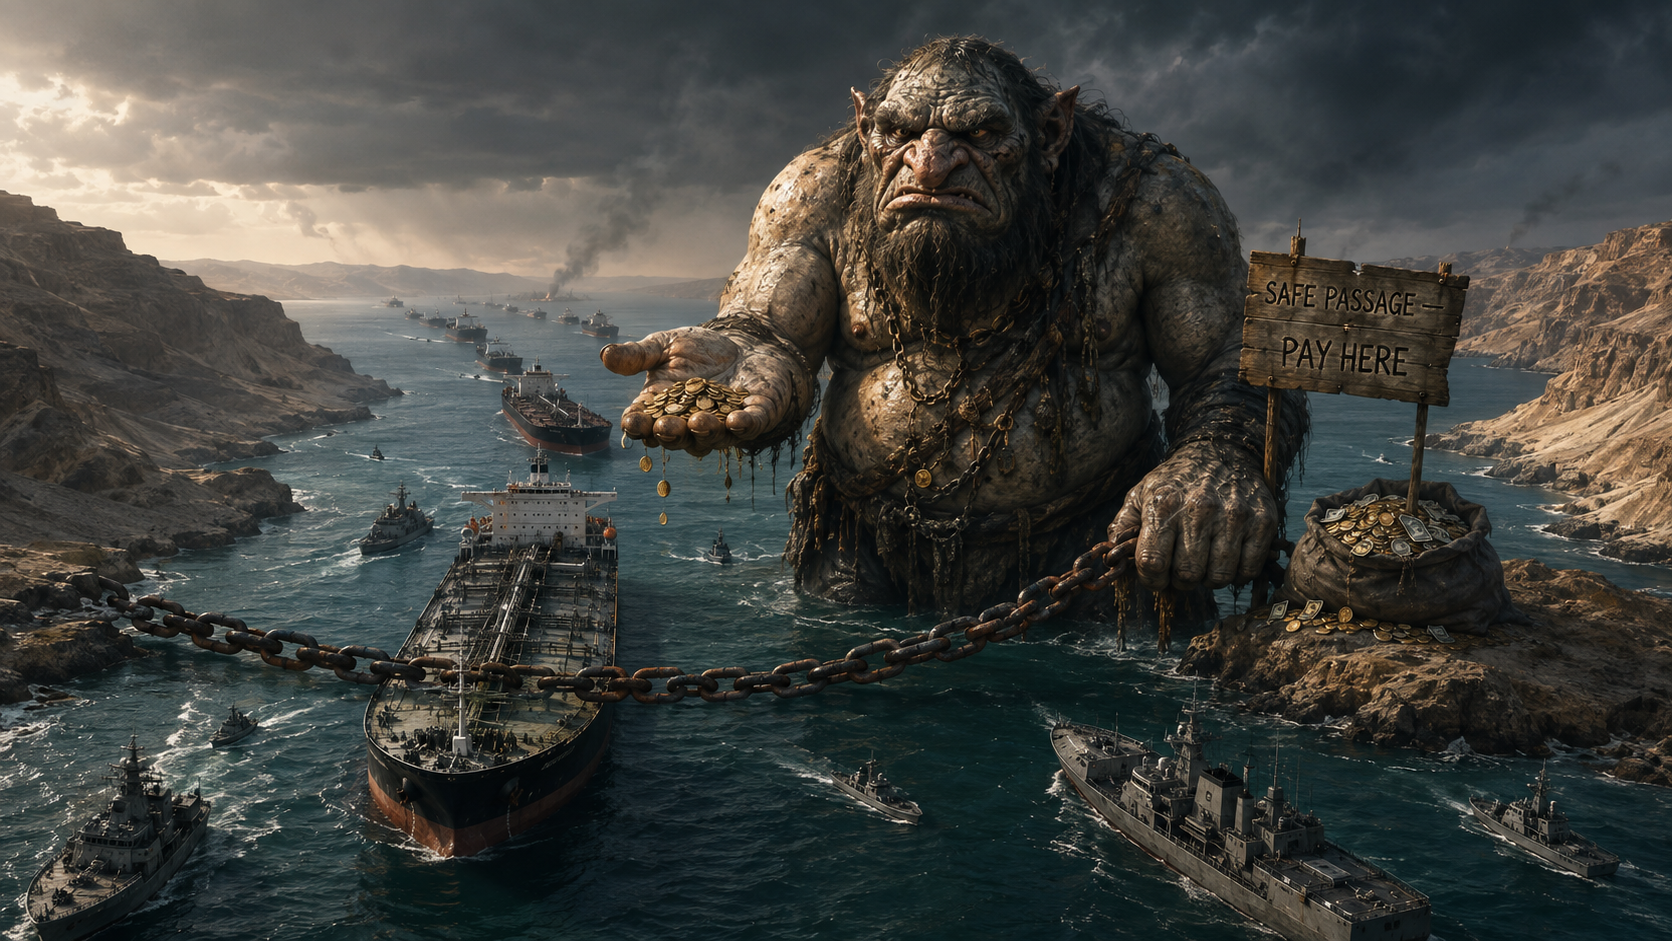
Every good troll story begins with a bridge.
The troll takes control of the crossing, blocks the road and demands payment from anyone wishing to pass.
Today, there is no bridge. There is a narrow stretch of water separating Iran from the Arabian Peninsula. But the principle is remarkably similar.
The Strait of Hormuz has become the world’s most important—and potentially most expensive—toll gate.
Ships may eventually move through it more freely. Agreements may be signed. Naval escorts may be arranged. Governments may announce that the Strait has “reopened”.
But the old Hormuz is gone.
The old normal was not simply ships moving through the water. It was the assumption that they would always be able to do so—freely, predictably and without first requiring geopolitical permission.
That assumption has now been destroyed.
The best possible outcome is no longer “back to normal”
Before the war, Hormuz was an internationally recognised shipping route through which commercial vessels passed without paying transit fees.
That mattered because approximately 25% of the world’s seaborne oil trade passed through the Strait in 2025. It also carried almost one-fifth of global liquefied natural gas trade.
The world treated that flow of energy as reliable.
It no longer can.
Traffic through Hormuz has repeatedly slowed to a trickle, despite ceasefires, agreements and military assurances. On 2 September, Iran expanded its blacklist to 56 vessels it considers non-compliant, threatening ships with fines, confiscation or detention if they attempt to use the waterway.
On the following day, just six commodity vessels reportedly passed through the Strait—well below even the heavily reduced recent average. Oil prices responded immediately as markets once again considered the possibility of further disruption. Reuters
This is not normal shipping.
It is conditional passage.
The most optimistic realistic outcome may now be a managed system under which ships can pass—but only after satisfying new security, insurance, political and possibly financial requirements.
In other words, the best-case scenario may still involve paying the troll.
A toll in everything but name
Iran has reportedly sought fees equivalent to between 5% and 7% of the value of cargoes passing through Hormuz. Proposals involving Oman have included fees of around 3%, while the United States has maintained that there should be no charges at all.
The world’s leading shipping associations have described such proposals as a “toll in all but name”, warning that they could undermine the established principle of free passage through international straits. Reuters
The sums involved are enormous.
A 5% charge on a cargo valued at £100 million would represent an additional £5 million simply for permission to pass. At 7%, the cost would rise to £7 million—and that is before insurance, fuel, crew, escort and financing costs are considered.
Whether Iran ultimately succeeds in imposing a formal toll is almost beside the point.
Because the ships will be paying tolls anyway.
They may be called:
- Transit fees
- Security charges
- War-risk insurance
- Naval escort costs
- Crew danger payments
- Higher charter rates
- Compliance and legal expenses
- Emergency-route surcharges
The description may change. The economic result does not.
Safe passage, once treated as a right, is becoming a service—and services have a price.
Insurance: the toll that already exists
Even if international pressure prevents a formal levy, the insurance market has already created a de facto one.
Before the conflict, insuring a tanker against war risks in the region could cost approximately 0.25% of the vessel’s value. As the fighting intensified, quoted rates rose towards 3%.
For a tanker valued between $200 million and $300 million, that could mean a war-risk premium of approximately $7.5 million—up from around $625,000 before the conflict. Reuters
That is potentially millions of dollars added to a single voyage without producing one additional barrel of oil, tonne of fertiliser or unit of economic value.
It is simply the price of risk.
And somebody must pay it.
Initially, that may be the shipowner, charterer, commodity trader or energy producer. But businesses rarely absorb permanently higher costs out of charity. They pass them through the chain.
Eventually, the toll reaches the refinery, manufacturer, farmer, supermarket—and consumer.
The world cannot simply sail around it
The obvious response is to find another route.
Unfortunately, geography does not negotiate.
Saudi Arabia and the United Arab Emirates have pipelines capable of redirecting some oil exports towards terminals outside Hormuz. However, the International Energy Agency estimates their available bypass capacity at approximately 3.5 million to 5.5 million barrels per day.
That provides some relief, but it cannot replace the enormous volume normally travelling through the Strait. Iran, Iraq, Kuwait, Qatar and Bahrain remain heavily dependent upon Hormuz for their exports.
For liquefied natural gas, the problem is even more severe.
More than 110 billion cubic metres of LNG passed through Hormuz in 2025. Approximately 93% of Qatar’s LNG exports and 96% of those from the UAE used the Strait—and according to the IEA, there are no alternative routes capable of bringing those volumes to market. International Energy Agency
Pipelines can be constructed. Export terminals can eventually be expanded. New supply agreements can be negotiated.
But none of that is quick, simple or inexpensive.
The world can reduce its dependence on Hormuz—but only by spending vast amounts of money. That spending is itself another form of toll.
This is about much more than oil
Hormuz is often described as an oil story.
That dramatically understates its importance.
More than 30% of global urea trade passes through the Strait, alongside approximately 20% of internationally traded ammonia and phosphate.
These are not obscure industrial products. They are essential agricultural inputs.
Restrict fertiliser supplies and farming becomes more expensive. Reduce fertiliser use and crop yields can suffer. Either route ultimately threatens higher food prices.
Around half of global seaborne sulphur trade also passes through Hormuz. Sulphuric acid is required in fertiliser production, chemical manufacturing, petroleum refining and the processing of critical minerals including copper, nickel and zinc.
The Gulf region also produces approximately 8% of the world’s aluminium, with around five million tonnes shipped through the Strait each year.
Therefore, the Hormuz toll does not stop at petrol pumps.
It can flow into:
- Diesel and aviation fuel
- Electricity and heating
- Fertiliser and food
- Plastics and chemicals
- Aluminium and construction
- Copper and critical minerals
- Manufacturing and transportation
- Shipping and insurance
This is how disruption in one narrow waterway travels through the entire global economy.
A permanent risk premium
Markets have memories.
Insurers remember damaged ships. Company boards remember stranded cargoes. Governments remember supply shortages. Investors remember emergency interventions. Crews remember sailing through waters in which commercial vessels became military targets.
That memory cannot be erased by a press conference announcing that the Strait is open.
Once a vulnerability has been exposed, markets begin pricing the possibility that it could happen again.
Insurers demand greater premiums. Shipping companies require stronger guarantees. Importers hold larger inventories. Governments build strategic reserves. Businesses seek alternative suppliers. Traders add a geopolitical premium to commodity prices.
All of these measures cost money.
That is why Hormuz will never truly return to normal.
Ships may again pass in greater numbers, but they will do so under the shadow of what has already happened—and what could happen again.
The physical waterway may reopen. The risk premium will remain.
From energy shock to inflation shock
This creates an uncomfortable problem for central banks.
Higher energy and commodity costs feed inflation. But the same disruption also damages economic growth by raising costs for businesses and reducing consumers’ disposable income.
That produces the possibility of a particularly unpleasant combination:
Higher inflation and weaker growth.
Central banks must then choose between keeping interest rates elevated to fight inflation or cutting them to support the economy.
Neither option is painless.
Higher rates increase mortgage payments, corporate refinancing costs and government debt-servicing bills. Lower rates risk weakening currencies and allowing inflation to become embedded.
The Hormuz toll therefore reaches beyond commodity markets. It can influence inflation expectations, interest-rate policy, bond yields, currencies, government borrowing and household finances.
A narrow waterway in the Middle East can affect the cost of a mortgage in Britain.
That is how interconnected—and vulnerable—the modern financial system has become.
Why this matters for gold
Gold does not require Hormuz to remain completely closed in order to benefit from the consequences.
It does not even require the worst-case scenario.
A prolonged period of conditional passage, higher insurance costs, intermittent disruption and geopolitical uncertainty would be enough to reinforce several of gold’s most important structural drivers:
- Persistent inflationary pressure
- Greater volatility in energy and commodity prices
- Slower global economic growth
- Higher government borrowing
- Pressure on sovereign bond markets
- Currency uncertainty
- Increasing geopolitical risk
- Declining confidence in governments and institutions
Gold cannot prevent a tanker from being attacked or a fertiliser shipment from being delayed.
What it can provide is an asset held outside the debt-based financial system, with no corresponding issuer and no dependency upon the promise of a government, bank or company.
That does not mean gold will rise every day or move in a straight line. No asset does. But it helps explain why both private investors and central banks continue to treat gold as strategic financial insurance against a world becoming less predictable.
In the World Gold Council’s 2026 survey, 89% of central banks expected official global gold reserves to increase over the following 12 months, while a record 45% expected to increase their own holdings. World Gold Council
They are not preparing for a return to the old normal.
They are preparing for whatever replaces it.
The troll remains
The Strait of Hormuz may eventually become safer.
More tankers may begin moving. New agreements may be negotiated and naval forces may succeed in providing greater protection.
But none of those outcomes restores what has been lost: the unquestioned belief that one of the world’s most important trade routes will remain permanently open, free and beyond the reach of geopolitical extortion.
From now on, every vessel must consider the troll.
Who controls the waterway? Who provides protection? Who grants permission? Who accepts the risk—and how much will they charge?
Those questions now carry a price.
Hormuz may reopen. The ships may begin moving again.
But the troll will remain.
And from now on, the world pays to pass.
About the author
Matthew Jones is Co-founder and Precious Metals Analyst at Britannia Bullion.
This article represents his personal analysis and opinion. It is intended for general information and does not constitute personal financial advice or a recommendation to buy or sell any asset.
Investment in physical gold is unregulated in the UK and is not protected by the FSCS or Financial Ombudsman Service. Its value can rise or fall, and ownership, custody, insurance and storage arrangements must be properly understood.
|
Matthew Jones Co-Founder Precious Metals Analyst Britannia Bullion |