Is now the right time—and can you trust the company taking your money?
Matthew Jones | Co-founder & Precious Metals Analyst
Britannia Bullion | 2 September 2026
Most people considering gold have dozens of questions.
Which coins should I buy? Should I choose bars instead? Where will my gold be stored? What happens if the price falls? Can I sell it again? Is gold better than leaving money in the bank?
All are reasonable. But beneath them sit two much bigger questions:
- Is now a good time to buy gold?
- Can I trust the company selling it to me?
The first question is about gold.
The second is about us.
Both deserve clear, honest answers. If you cannot answer both confidently, you should not buy yet. Gold should reduce financial uncertainty—not introduce a new source of it.
Question One: Is Now a Good Time to Buy Gold?
The honest answer begins with another question:
What do you expect gold to do for you?
If you are trying to make a quick profit over the next few weeks, nobody can reliably tell you whether today is the perfect entry point. Gold can rise or fall sharply over short periods. Interest-rate expectations, currencies, investment flows and political events can all move the price unexpectedly.
If, however, you are buying gold to diversify savings, protect purchasing power and reduce dependence upon the banking and financial system, the more relevant question is not where gold might trade next Tuesday.
It is how the world may look several years from now.
At Britannia Bullion, we believe physical gold should generally be approached with a minimum five-year view. That does not mean the price will rise every year or that five years guarantees a profit. It means gold is better judged across an economic cycle than across a handful of trading sessions.
A Substantial Discount From the High
At the time of writing, the UK gold price is approximately £3,220 per troy ounce, compared with a 2026 high of just over £4,068. That places gold roughly 21% below its recent UK peak. The Royal Mint
In US dollars, the correction is larger still. Spot gold is trading near $4,300, having reached approximately $5,608 in January—a fall of around 23% from the high.
That is a substantial discount. It does not prove that the lowest price has been reached, and gold could certainly fall further. But investors considering gold today are no longer being asked to buy at the top of the market.
They are being offered the same asset—and broadly the same long-term case—at a materially lower price.
Why Has Gold Fallen During an Inflation Scare?
The recent price action can initially appear contradictory.
Conflict and higher energy prices increase the danger of inflation. Inflation is normally considered supportive of gold. Yet gold has recently fallen as those same inflation fears have intensified.
The explanation lies in the market’s immediate reaction.
Investors fear that renewed inflation will force central banks—particularly the US Federal Reserve—to increase interest rates or keep them elevated for longer. Higher interest rates raise the return available from cash and bonds. They can also strengthen the dollar, making dollar-priced gold more expensive for international buyers.
On 2 September, traders were pricing a 68% probability of a US rate increase at the Federal Reserve’s next meeting. A stronger dollar and rapidly changing rate expectations pushed spot gold to its lowest level in more than three weeks. Reuters
In other words, markets are currently responding to the expected short-term policy reaction rather than the longer-term economic problem.
Central banks may raise rates to fight inflation. But higher rates also increase borrowing costs for heavily indebted governments, businesses and households. They can weaken economic growth, place pressure on financial markets and make existing debt more difficult to service. If policymakers later respond by cutting rates, creating liquidity or tolerating higher inflation, the underlying monetary case for gold can re-emerge.
This produces an important distinction:
The market is pricing the next interest-rate meeting. A gold investor should be considering the next five years.
What Does the Five-Year View Show?
Nobody knows precisely where gold will trade in five years. What we can assess are the forces likely to influence it.
Those forces remain formidable.
Government Debt and Borrowing Costs
Governments continue to carry historically large debt burdens. Higher interest rates do not remove that debt; they make refinancing it more expensive. More public money must then be directed towards interest payments rather than services, investment or tax reductions.
This leaves governments with uncomfortable choices: spend less, tax more, borrow more or allow inflation gradually to reduce the real value of what they owe.
None is politically or economically painless.
Inflation Has Not Disappeared
Inflation may fall for periods, but the forces capable of reviving it remain: energy shocks, war, supply disruption, trade barriers, labour shortages and continued government spending.
The current market concern about renewed inflation demonstrates that the problem was suppressed, not necessarily defeated permanently.
Geopolitical Fragmentation
The global financial system is becoming more divided. Wars, sanctions, frozen reserves and competition between major powers have encouraged governments to reconsider where and how national wealth should be held.
Gold is nobody else’s currency and, when owned outright, nobody else’s liability.
Central Banks Are Still Buying
Central banks have accumulated an average of approximately 1,000 tonnes of gold annually over the last four years, roughly double the average of the preceding decade.
In the World Gold Council’s 2026 survey, 89% of respondents expected global central-bank gold reserves to increase over the following 12 months. A record 45% expected their own institution to increase its holdings. The reasons included crisis performance, diversification, inflation protection and geopolitical risk. World Gold Council
These institutions are not attempting to predict next week’s gold price. They are positioning national reserves for the world they expect over the coming years.
Supply Cannot Be Expanded Quickly
Gold supply does not respond rapidly to higher prices. Discovering, permitting and developing a mine can take many years. In the second quarter of 2026, total gold supply was broadly unchanged from the previous year, despite prices remaining historically elevated. Mine production increased by only 2%. World Gold Council
Gold’s scarcity has not altered simply because its market price has corrected.
Is Gold Better Than Money in the Bank?
This is the wrong comparison if it is treated as an all-or-nothing choice.
Cash and gold perform different jobs.
Cash is useful for bills, emergencies and money that may be required at short notice. It offers immediate access and certainty over its nominal value. Sensible financial planning normally requires an appropriate cash reserve.
Gold is generally better suited to money that will not be needed immediately. Its purpose is to provide diversification, longer-term purchasing-power protection and ownership of an asset outside the promises of a bank, company or government.
Gold does not pay interest. Its price can fall. Buying and selling involve premiums or spreads, and secure storage or insurance may involve costs.
Cash carries a different risk. Its number may remain stable while inflation reduces what that number can purchase. Interest can partly offset that loss, but interest may be taxed and deposit rates do not always keep pace with the rising cost of living.
The question is therefore not necessarily gold or the bank.
It is whether too much of your long-term wealth is dependent upon cash, one currency and one financial system.
Should You Buy Everything at Once?
A substantial price correction can create an attractive opportunity, but it does not remove uncertainty.
Some buyers are comfortable making one purchase and accepting that prices may move afterwards. Others prefer to divide their intended allocation into stages. Buying in tranches can reduce the emotional pressure of attempting to identify the precise bottom.
If gold falls again, later purchases can be made at lower prices. If it begins recovering, part of the intended holding has already been secured.
There is no single approach suitable for everybody. The appropriate amount depends on your cash requirements, other assets, debts, objectives and tolerance for price movements. Money required for near-term living costs should not be committed to a long-term asset.
The most important principle is to make a considered decision—not to buy through fear, pressure or a belief that any return is guaranteed.
Question Two: Can I Trust the Company Selling It to Me?
For many buyers, this is the more important question.
Gold is unfamiliar. The sums involved may represent years of savings, the proceeds of a property sale, an inheritance or money intended for retirement. Transferring that money to a company requires far more than a persuasive telephone conversation.
The prospect is really asking:
- Will my money genuinely purchase physical gold?
- Will I legally own what I have paid for?
- Will I receive exactly what was promised?
- What happens after I have transferred the funds?
- Can I take delivery?
- If it is stored, where is it and whose name is it held in?
- Is it insured?
- Can I sell it again?
- Will somebody still answer the telephone afterwards?
These questions should never be treated as an inconvenience. They are the questions a responsible buyer ought to ask.
Trust Should Be Evidenced, Not Requested
No gold company should expect to be trusted simply because it says the right things.
Before paying, a buyer should understand:
Who They Are Dealing With
Check the company’s legal identity, trading history, directors, physical location and contact details. Establish who will be responsible for your purchase and whether you can speak to a named person if something goes wrong.
Exactly What Is Being Purchased
The quotation and invoice should identify the product, quantity, weight, purity, condition and total price. Any premium above the underlying metal value should be understood before funds are transferred.
When Ownership Passes to You
If gold is being stored, determine whether specific metal is allocated to you and whether it is held in your name. Ask what documentary evidence confirms ownership and whether the dealer itself has access to, or control over, the metal.
Delivery and Storage Arrangements
Understand expected delivery times, insurance, identification requirements and who carries the risk while the gold is in transit. If using storage, ask who operates the vault, what it costs, how the holding is insured and how you can request withdrawal.
How You Can Sell
A buyer should consider the exit before making the purchase. Ask whether the company operates a buy-back service, how prices are determined, what documentation will be required and how quickly proceeds are normally paid.
What Is Not Guaranteed
Be wary of anybody promising a fixed return, a guaranteed future market value or a risk-free investment. A reputable company should explain that gold can fall as well as rise and should be willing to discuss the disadvantages as clearly as the potential benefits.
If a company avoids reasonable questions, applies excessive pressure or discourages independent checks, walk away.
How Britannia Bullion Answers the Trust Question
At Britannia Bullion, we do not believe trust should be requested. It should be earned—and supported by evidence.
So do not simply take our word for it. Visit us. Meet us. Watch us. Read our analysis. Examine our record and speak to the clients who have already dealt with us.
Meet Us Before You Buy
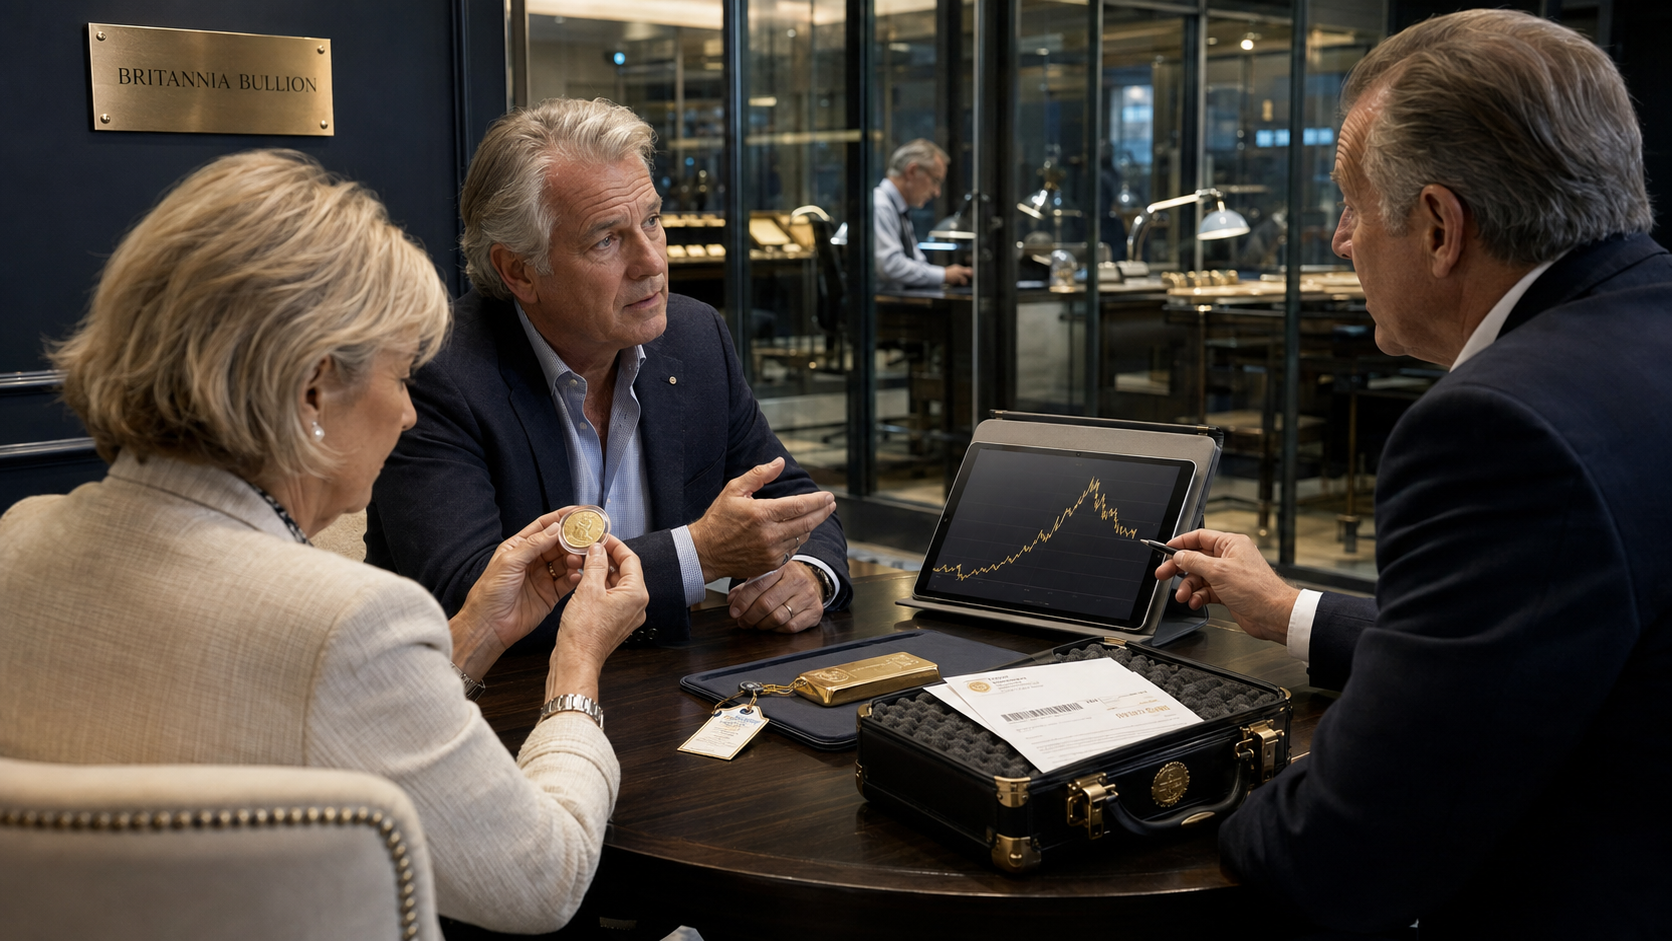
We actively encourage prospective clients to visit our premises in Hatton Garden and meet the people who will be handling their purchase. For those unable to visit, we can arrange a consultation in their own home or speak face to face by Zoom.
This matters because Britannia Bullion is not intended to be a faceless online operation or an anonymous voice at the end of a telephone. Clients should know who they are dealing with, where we are based and how to reach us before, during and after a purchase.
See Us in the Real World
We regularly attend and sponsor client events and major investor shows, giving prospective buyers the opportunity to meet our team, ask questions and challenge our thinking in person.
We also produce our own podcasts, webinars and ongoing market commentary. Our analysis is not hidden behind a sales conversation: it is placed in public, where it can be considered, questioned and judged over time.
Britannia Bullion’s in-house Precious Metals Analyst, Matthew Jones, also contributes analysis to Kitco.com, one of the international precious-metals market’s best-known news and analysis platforms.
Expertise should be visible. Opinions should be explained. Trust should be open to scrutiny.
Every Coin and Bar Is Tracked
Clients receive clear documentation showing exactly what they are purchasing and the price agreed. Physical products are sourced through established wholesale relationships.
For delivery orders, every individual bar and coin is tagged and tracked. Each consignment is fully insured until it reaches the client’s front door and, subject to cleared funds and final delivery arrangements, is normally delivered within 24 hours of purchase.
Most importantly, Britannia Bullion maintains a record of 100% fulfilment on every delivery order to date.
Put simply: every client who ordered delivery has received their gold.
Independent Storage and a Route Back Out
Clients can choose insured delivery or specialist independent storage, depending on their circumstances and the products purchased. Stored client metal is not held in Britannia Bullion’s own name. Ownership, charges and withdrawal arrangements are explained before the client proceeds.
We also operate a guaranteed buy-back scheme, so clients have a clearly established route to sell when the time comes. The applicable valuation and terms depend upon the product and market conditions and should always be understood at the point of purchase.
Judge Us by Our Clients
Our client reviews provide prospective buyers with the experiences of people who have already completed the process. They describe the service received, the communication provided and, crucially, the successful delivery of their gold.
We are proud of those reviews because they were not written in a marketing meeting. They were earned through real transactions with real clients.
The Relationship Continues
Our responsibility is not intended to end when payment is received. Clients receive ongoing market commentary and can continue speaking to us about their holdings, delivery, storage and eventual sale.
We do not ask prospective clients to suspend judgement. We give them several ways to test us: visit our premises, invite us to meet them, attend one of our events, join a webinar, listen to our podcasts, read our analysis, examine our reviews and check our delivery record.
That is how confidence should be built—not through a promise, but through proof.
Two Questions—One Important Decision
Is now a good time to buy gold?
Gold is currently available at a discount of approximately 21% from its recent UK high because markets are concentrating on the immediate prospect of higher inflation, higher interest rates and a stronger dollar. The price may fall further, and no responsible company should claim otherwise.
But when the view is extended from the next meeting of the Federal Reserve to the next five years, the principal forces supporting gold remain firmly in place: high government debt, pressure on currencies, recurring inflation risk, geopolitical fragmentation, constrained supply and sustained central-bank demand.
In our assessment, the long-term case looks as strong as ever. The price is simply lower.
Can you trust the company selling it?
Do not settle for reassurance. Look for evidence. Understand what you are buying, how you will own it, when it will arrive, where it will be stored and how it can eventually be sold.
We believe Britannia Bullion’s face-to-face accessibility, public analysis, strong client reviews, guaranteed buy-back scheme and 100% delivery-fulfilment record provide that evidence.
If either of the two central questions remains unanswered, do not buy yet.
But if gold is appropriate for your objectives, you can take a long-term view and the company has earned your confidence, today’s substantial discount may represent something increasingly rare:
An opportunity created by short-term market fear—within a long-term story that has not materially changed.
About the Author
Matthew Jones is Co-founder and Precious Metals Analyst at Britannia Bullion. This article represents his personal analysis and opinion. It is intended for general information and does not constitute personal financial advice or a recommendation to buy or sell any asset.
Investment in physical gold is unregulated in the UK and is not protected by the FSCS or Financial Ombudsman Service. Its value can rise or fall, and ownership, custody, insurance and storage arrangements must be properly understood.
|
Matthew Jones Co-Founder Precious Metals Analyst Britannia Bullion |