Wars, Fuel and Food Shortages: The Inflationary Storm Approaching Britain
It may begin with an oil tanker thousands of miles from Britain.
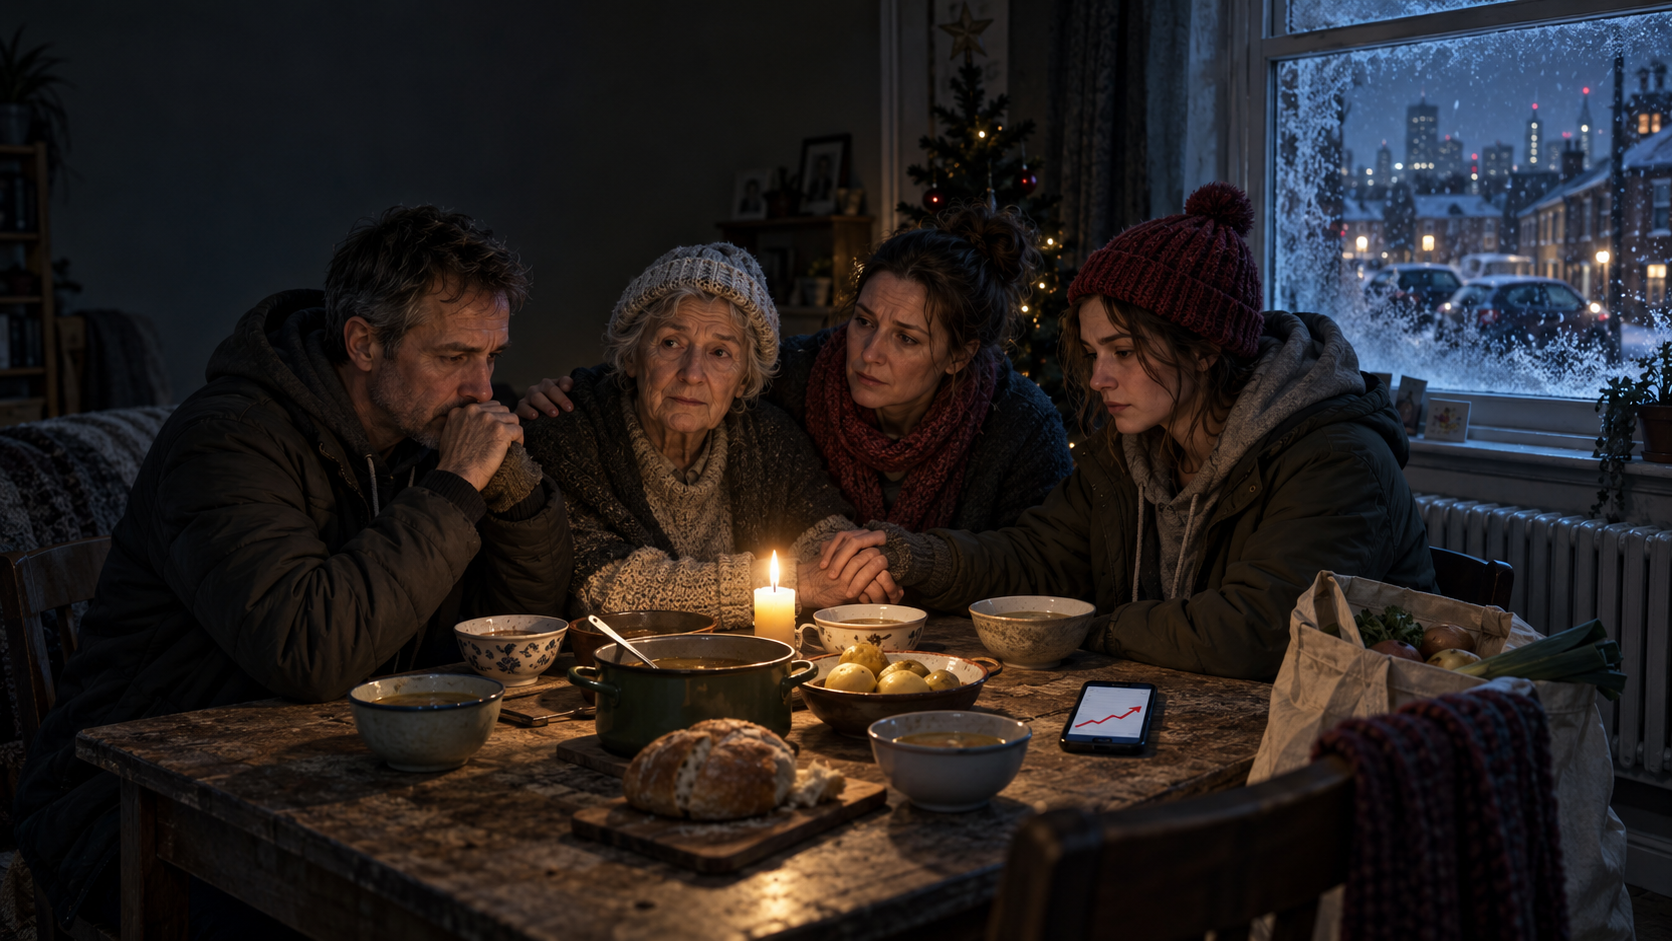
A vessel is attacked. Insurance costs rise. Deliveries are delayed. Refineries compete for increasingly scarce crude. Diesel and jet fuel become more expensive. Farmers pay more to operate machinery and purchase fertiliser. Hauliers increase their charges. Supermarkets pass those costs through to families. Heating bills rise just as temperatures begin to fall.
Individually, each increase may appear manageable.
Together, they could create a winter of discontent.
Britain is now approaching the colder months while two major wars destabilise global energy supplies, commercial oil inventories are falling, European gas storage remains vulnerable and the cost of transporting almost everything is rising.
These are not separate problems.
War, oil, diesel, food, heating bills and inflation are parts of the same economic chain—and that chain ultimately reaches every British household.
Wars Do Not Remain on Battlefields
Wars may begin with missiles, drones and soldiers, but their economic consequences travel much further.
They move through pipelines, shipping lanes, refineries, ports and electricity grids. They arrive in factories, farms, airports, supermarkets and eventually household bank accounts.
The continuing Russia–Ukraine war has already transformed Europe’s energy market. Europe reduced its reliance on Russian oil and gas, but it replaced secure pipeline supplies with a more expensive and increasingly competitive dependence on internationally traded energy.
That system is now being tested by another conflict.
The Iran war and continuing disruption around the Strait of Hormuz have placed a critical proportion of global energy supplies at risk. The Strait ordinarily carries approximately one-fifth of internationally traded oil, as well as significant volumes of liquefied natural gas and refined petroleum products.
Iran has demonstrated that it can threaten vessels attempting to use the waterway. The United States has attacked Iranian tankers. Iranian forces have targeted ships they describe as non-compliant, while attacks involving regional energy infrastructure have continued.
Hormuz is no longer simply a narrow shipping lane.
It has become one of the most expensive geopolitical toll gates in the world.
The Oil Shock Has Already Arrived
Brent crude has returned above $100 per barrel following the latest escalation between Iran and the United States.
But the price on a trading screen tells only part of the story.
The US Energy Information Administration estimates that global oil inventories have already fallen by approximately 400 million barrels during 2026. Middle Eastern production shut-ins reached 6.7 million barrels per day in August, and the EIA expects them to average around 5.7 million barrels per day during the final quarter of the year.
Normal production and exports are not expected to return before the second quarter of 2027. Reuters
That matters because the world has been absorbing the disruption by drawing down inventories, releasing strategic reserves, rerouting tankers and sourcing supplies from further away.
Those measures can delay a shortage. They cannot manufacture oil.
Every barrel taken from storage reduces the protection available against the next attack, damaged refinery, closed port or interrupted shipping route.
The market is not only paying for fuel. It is paying for longer journeys, limited tanker availability, war-risk insurance, naval protection and the possibility that a cargo may never reach its destination.
That additional cost must eventually be paid by someone.
The First Shortage Will Not Look Like a Shortage
When people hear the word “shortage,” they imagine closed petrol stations and motorists queuing around the block.
That is normally one of the final stages.
Modern fuel shortages begin more quietly.
An airline is told that its usual allocation is unavailable. An independent forecourt cannot obtain fuel at a commercially viable price. A haulage company receives less diesel than it ordered. A refinery prioritises contracted customers over buyers in the spot market. A supplier protects emergency services, public transport and major food distributors by restricting deliveries elsewhere.
Fuel may still be physically available—but not for everyone, in every location, at the price they previously expected.
This is demand management by another name.
Governments do not need to announce formal rationing for consumption to be reduced. High prices, restricted allocations, cancelled flights, fuel surcharges and declining industrial activity can accomplish much of the same objective.
The market simply prices some users out.
Jet Fuel: The Early Warning
Jet fuel is particularly vulnerable.
Europe has been replacing disrupted Gulf supplies by importing fuel from the United States and Asia, increasing refinery output and drawing down stocks.
In April, oil-market analysts warned that if normal Gulf shipping failed to return, Europe’s available jet-fuel supplies could be exhausted by the end of the third quarter. Reuters
Emergency imports and changing supply routes prevented that forecast from becoming an immediate crisis. But those interventions did not rebuild a comfortable cushion. They bought time.
Airlines are therefore likely to experience the first stage of fuel stress before most motorists notice anything unusual.
The response may include reduced schedules, cancelled marginal routes, higher ticket prices, additional fuel surcharges and priority being given to major hubs or strategically important flights.
Longer routes avoiding dangerous airspace also consume more fuel, placing further pressure on supplies precisely when availability is constrained.
The public may be told there is no national shortage while individual airlines and airports are already being instructed to manage demand.
Both statements can be true.
Diesel Connects Oil to Everything Else
Diesel is the bloodstream of the physical economy.
It powers lorries, delivery vans, tractors, construction equipment, generators and a substantial part of Britain’s industrial machinery.
When diesel becomes more expensive, the cost of almost every physical product rises with it.
Food must be planted, fertilised, harvested, processed, refrigerated, transported, stored and delivered. Energy is required at every stage.
A supermarket product does not need to contain oil for its price to be driven by oil.
The plastic packaging may be derived from hydrocarbons. The fertiliser used on the crop may depend upon natural gas. The tractor uses diesel. The processing plant consumes electricity. The refrigerated lorry burns fuel. The distribution centre pays higher heating and operating costs.
By the time the product reaches the shelf, the energy shock has been added repeatedly.
That is how a distant conflict arrives at the family dinner table.
The Fertiliser Problem
The Gulf is not only important for oil and gas. It is also a major source of internationally traded fertiliser and the natural-gas feedstocks required to manufacture it.
Fertiliser production is highly energy-intensive. When gas becomes scarce or prohibitively expensive, manufacturers reduce production or suspend operations.
Farmers are then confronted with a difficult choice:
- absorb substantially higher costs;
- use less fertiliser and accept lower crop yields;
- change what they plant;
- or pass the additional expense through the supply chain.
None of those options produces cheaper food.
The effect may not be immediate because agricultural cycles take time. A fuel disruption today can influence planting decisions, yields and food prices months later.
This creates the danger of a rolling crisis: the initial oil shock affects transport almost immediately, while the fertiliser shock reaches consumers through future harvests.
Even if the fighting stops, those lost growing seasons cannot be recovered retrospectively.
Food Shortages Rarely Begin With Empty Shelves
Britain is unlikely to wake one morning and discover that every supermarket has run out of food.
The deterioration would be gradual.
Some products become more expensive. Imported goods arrive less reliably. Retailers reduce the number of choices available. Fresh produce suffers from transport delays. Suppliers stop producing low-margin items. Shrinkflation returns. Promotions disappear. Households substitute cheaper products until demand overwhelms those alternatives too.
There is still food—but less variety, lower availability and a much higher cost.
For wealthier households, this is inflation.
For poorer households, it becomes a shortage because the product still exists but is no longer affordable.
That distinction matters.
A country does not need to run out of food to experience a food crisis. It simply needs a growing proportion of its population to struggle to purchase what remains available.
Heating Bills: The Crisis Enters the Home
The timing could hardly be worse.
European gas stocks are entering the winter from an unusually weak position, while competition for liquefied natural gas is increasing. Europe must compete with Asian buyers for cargoes that can be redirected toward whichever market offers the highest price.
At the same time, Russia is reminding Europe that cheaper Russian gas remains available—if governments are prepared to reverse their political position.
This is not generosity. It is leverage.
Russia understands that public support for sanctions and military assistance can weaken when voters are cold, businesses are closing and household bills are climbing.
The Kremlin does not need Europe to become politically sympathetic toward Russia. It only needs European populations to become exhausted by the cost of opposing it.
For British households, rising wholesale gas and electricity costs will eventually filter through into higher bills. The energy-price cap can delay or smooth that adjustment, but it cannot permanently prevent global costs reaching consumers.
A price cap changes when people pay.
It does not change what the energy costs.
Inflation’s Unwelcome Return
Britain has already experienced the damage caused by a rapid inflationary shock.
Savings lost purchasing power. Food and energy bills increased. Mortgage costs rose. Businesses faced higher wages and input costs. The Bank of England increased interest rates in an attempt to restrain demand.
The public was repeatedly told that inflation would prove temporary.
It did not feel temporary to anyone paying the bills.
Now the next inflationary impulse may be arriving before the previous one has been fully repaired.
This presents central banks with an almost impossible problem.
Higher oil and food prices do not necessarily result from excessive British consumer demand. They arise because global supplies have been disrupted.
Increasing interest rates cannot reopen the Strait of Hormuz. It cannot rebuild a refinery, protect a tanker, manufacture fertiliser or end a war.
But if the Bank of England does not respond, inflation expectations may become embedded. If it does respond, households and businesses face higher borrowing costs during an economic slowdown.
The choice becomes brutally simple:
accept higher inflation or impose greater economic pain in an attempt to contain it.
Neither outcome protects the value of cash.
Britain’s New Winter of Discontent
The original Winter of Discontent became synonymous with strikes, shortages, inflation and a country losing confidence in its economic direction.
The circumstances today are different, but the ingredients are becoming uncomfortably familiar:
- wars with no credible conclusion;
- threatened shipping routes;
- falling oil inventories;
- vulnerable fuel supplies;
- higher transport and agricultural costs;
- rising food prices;
- increasing heating bills;
- weak economic growth;
- and public frustration with governments that appear unable to control events.
The danger is not simply that one of these pressures becomes unmanageable.
It is that they arrive together.
A household may be able to absorb a higher heating bill. It may be able to absorb more expensive food. It may survive another increase in mortgage or rental costs.
But when heating, food, transport, borrowing and taxation all rise simultaneously, financial resilience disappears remarkably quickly.
That is when an economic problem becomes a political and social one.
Why Gold Matters
Gold cannot prevent wars, reopen shipping lanes or reduce the cost of diesel.
What it can do is provide protection against the monetary consequences.
Energy and food shocks weaken currencies by increasing the amount of money required to purchase the same essential goods. Governments often respond with subsidies, tax relief, emergency support and additional borrowing. Central banks face pressure to accommodate those policies while avoiding a deeper recession.
The result is usually more debt, greater currency debasement and further erosion of purchasing power.
Gold sits outside that system.
It is not issued by a government facing an election. It cannot be created to subsidise energy bills. It does not depend upon a central bank maintaining credibility or a heavily indebted state honouring its promises in full.
It is a finite, internationally recognised asset that has preserved wealth through wars, inflationary shocks, currency failures and political upheaval for thousands of years.
This is why central banks continue buying it.
It is why China is accumulating it and building new gold-trading, clearing, vaulting and settlement infrastructure around it.
And it is why private investors increasingly view physical gold not as a short-term speculation, but as long-term financial insurance.
Preparing Before the Storm
Investors cannot control the weather, the wars, the price of oil or the decisions made by central banks.
They can control how their wealth is positioned.
Waiting until fuel is being allocated, supermarket prices are accelerating and heating bills are rising means waiting until the crisis has become obvious to everyone.
By then, markets will already have reacted.
Wealth preservation is not about predicting the exact date of the next shortage or the precise level of inflation. It is about recognising when multiple risks are moving in the same direction and acting before those risks become a national emergency.
Britain is now approaching winter with depleted global oil inventories, disrupted energy supplies, continuing wars and renewed inflationary pressure.
The storm is no longer somewhere over the horizon.
It is moving through the shipping lanes, the refineries and the wholesale markets—and toward every British home.
A winter of discontent is approaching.
The question for investors is not whether the Government will find another temporary intervention.
It is whether their wealth is prepared for what happens when temporary solutions finally run out.
About the Author
Matthew Jones is Co-Founder and Precious Metals Analyst at Britannia Bullion, a UK precious-metals company specialising in physical gold ownership and long-term wealth preservation. Matthew provides market analysis and commentary on gold, monetary policy and geopolitical risk, including contributions to Kitco News.
Important Information
This article is provided for general information and education only and does not constitute personal financial, investment, tax or legal advice. The value of gold can rise as well as fall, and past performance is not a reliable indicator of future results. Investors should consider their individual circumstances and, where appropriate, seek independent professional advice.
|
Matthew Jones Co-Founder Precious Metals Analyst Britannia Bullion |